


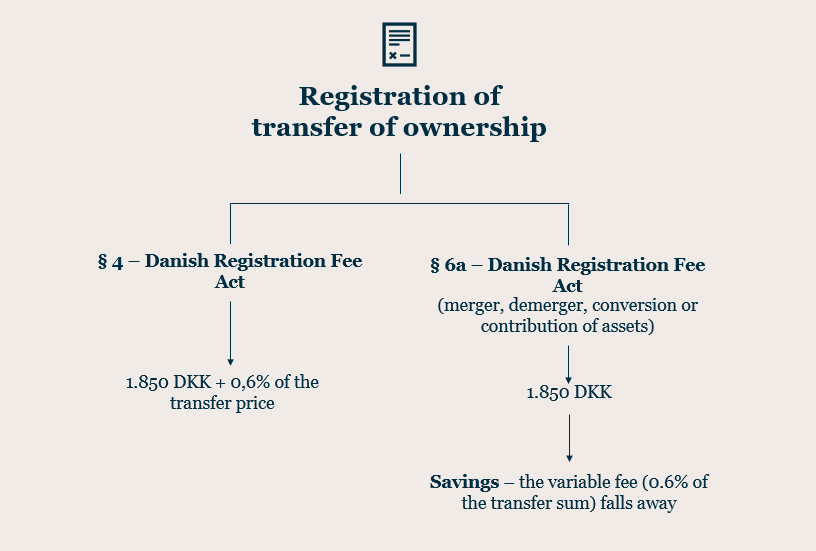
Section 4 of the Danish Registration Fee Act provides that registering a change in the ownership of real estate or shares therein incurs a registration fee of DKK 1,850 plus 0.6% of the transfer price.
Section 6 a of the Danish Registration Fee Act provides an exception to this rule, whereby the registration of changes in title for “companies etc.” resulting from a merger, demerger, conversion or contribution of assets triggers only the fixed fee of DKK 1,850 – with no variable fee. According to the legislative history of this provision, such transactions are not regarded as a transfer of title for registrations fee purposes. For major corporate reorganisations, qualifying for the exemption can therefore represent substantial savings.
The term “companies etc.” is not explicitly defined in the Danish Registration Fee Act, and the scope of section 6 a must therefore be determined based on the legislative history and case law:
The case concerned an individual who converted his personally owned agricultural business into a newly established limited partnership company (P/S), transferring several real properties to the new entity as part of the conversion. The Danish Tax Agency had held that the variable fee exemption in section 6 a of the Danish Registration Fee Act did not apply because the conversion of the partnership to a limited partnership company did not meet the requirements of the Business Conversion Act, which only permits tax-free conversion into a public or private limited liability company.
The National Tax Tribunal disagreed, ruling that compliance with the Business Conversion Act is not a prerequisite for section 6 a to apply, even if the conversion does not satisfy the conditions for a tax-free conversion, provided that the conditions established in practice are met.
As the business’s full set of assets and liabilities had been transferred to the newly incorporated company solely in exchange for equity interests and the owner held 100% of the company at the time of the transfer, the Tribunal found that the conditions under section 6 a were met. Consequently, the additional variable registration fee assessed by the Tax Agency – amounting to more than DKK 350,000 in total – was dismissed entirely.
The ruling reinforces a clear trend. Danish authorities and courts are shifting their focus from a strict interpretation of section 6 a to a more substance-based approach, considering factors such as continuity of ownership and consideration. This is a timely reminder that:
Gorrissen Federspiel’s Real Estate and M&A teams regularly advise on corporate reorganisations and real estate transactions in Denmark. This includes advising on the registration fees that often follow from such transactions. We can assist with:
We are happy to provide a specific assessment of your matter, whether it concerns a reorganisation, a transaction, or any other type of real estate matter.